


 Login
 Blog
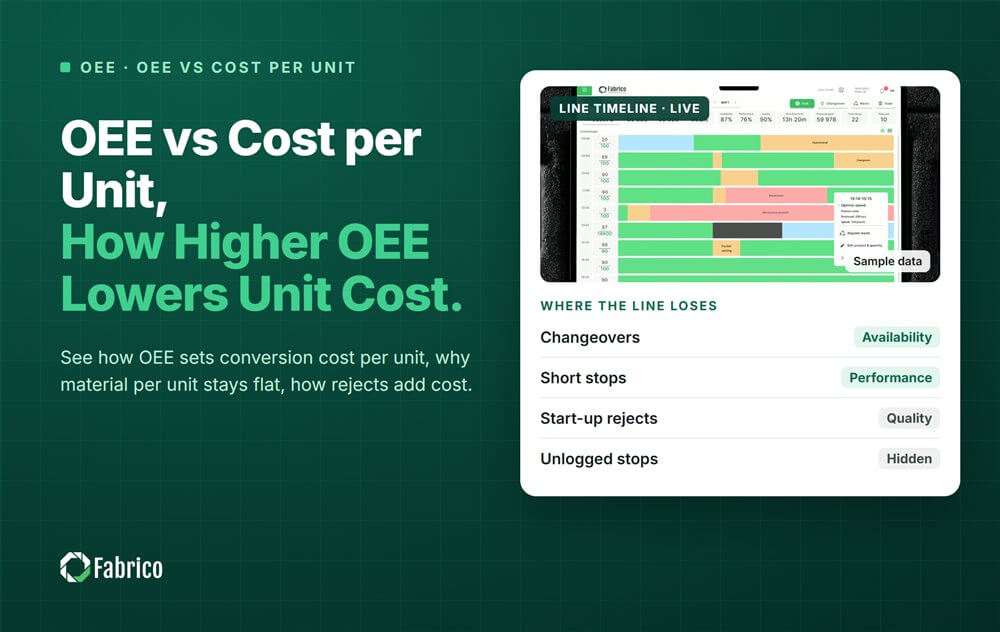
OEE vs Cost per Unit: How Higher OEE Lowers Unit Cost

Key takeaways
- Conversion cost per unit is the cost of running the line for an hour divided by the good units it makes in that hour.
- Higher OEE (overall equipment effectiveness) spreads the same hourly cost over more good units, so unit cost falls.
- Material per good unit stays the same, but each reject adds material you paid for and threw away.
- A lower unit cost on paper is cash only when the extra output sells or a real cost goes.
- Use good units, not total units, and the measured rate, not the planned one.
OEE and cost per unit are linked through one formula. Conversion cost per unit is the cost of running the line for an hour divided by the good units it makes in that hour. Raise OEE and the same hourly cost spreads over more good units. Material per unit stays flat, while rejects add material you threw away.
End of the month on the mouthwash line. Finance shows unit cost up again. The line team already knows why: two long changeovers and a capper that kept jamming on nights.
This guide is for plant managers, controllers and OpEx (operational excellence) leads in FMCG (fast-moving consumer goods) groups. They link line performance to standard cost. It covers the formula, scrap, and when a lower unit cost is cash. It comes from Fabrico, a platform for OEE and light MES (manufacturing execution system) with computer vision on stops.
What is cost per unit made of?
Cost per unit has two main parts: the material in the unit and the cost of converting it on the line. OEE moves the second part directly, and the first only through rejects.
- Material per unit: product, bottle, cap, label and the case share. The recipe and the pack fix it per good unit.
- Conversion cost per unit: line labour, energy, overhead and depreciation for an hour, divided by the good units made in that hour.
- Scrap material per unit: the material in rejects, spread over the good units that shipped.
Finance calls the second part conversion cost: labour and overhead absorbed per unit. It is where OEE shows up on the cost sheet.
How does OEE change cost per unit?
OEE sets how many good units the line makes per hour. Conversion cost per unit is the hourly cost divided by that number. The formula is short.
- Good units per hour = rated speed per hour x OEE.
- Conversion cost per unit = line cost per hour / good units per hour.
The link is not a straight line. Each OEE point removes more cost on a weak line than on a strong one. On the weak line, the same hour is shared by fewer units to start with.
Our OEE calculation guide shows how to measure the OEE that goes in. Our article on turning OEE losses into cost visibility maps each OEE factor to a cost category.
Why do rejects cost more than lost minutes?
A stop costs line time. A reject costs line time and the material inside it, so a point lost to rejects costs more than a point lost to stops.
- Rejects need the line hour to make them and the material to fill them.
- Start-up rejects after a changeover add to the cost of that changeover.
- Rework is not good output. It uses line time again and hides the real yield.
- Count scrap once, at material cost, spread over the good units.
When is a lower unit cost real cash?
Only when the extra output sells or a real cost goes, such as overtime, a shift or a co-packer. If volume and fixed costs stay the same, the lower unit cost is an accounting result.
For why fixed costs do not fall with volume, see throughput accounting. For the maintenance share, see the maintenance cost per unit KPI (key performance indicator).
How do you report OEE and unit cost together?
Put them side by side, per line and per month, on the same definitions. Then a cost change can be traced to a loss, and a loss to a cost.
- OEE and its three factors.
- Good units per hour, measured from the machine.
- Conversion cost per good unit.
- Scrap material per good unit.
- Hours freed or lost against last month, and what happened to them.
A worked example: unit cost on a mouthwash line at two OEE levels
Sample line (illustrative numbers, not a customer): a 500 ml mouthwash line whose filler is rated at 3,000 bottles an hour. Material in each bottle costs $0.40.
Running the line costs $1,260 an hour. Of that, $1,140 is crew, overhead and depreciation that stay whatever the volume. The other $120 is energy, which goes with run hours.
| Per hour | Today | After the fixes |
|---|---|---|
| Bottles made | 1,890 | 2,142 |
| Rejects | 90 | 42 |
| Good bottles | 1,800 | 2,100 |
| OEE | 60.0% | 70.0% |
| Conversion cost per good bottle | $0.700 | $0.600 |
| Material per good bottle | $0.400 | $0.400 |
| Scrap material per good bottle | $0.020 | $0.008 |
| Total cost per good bottle | $1.120 | $1.008 |
- OEE today = 1,800 / 3,000 = 60.0%. After the fixes = 2,100 / 3,000 = 70.0%.
- Conversion cost = $1,260 / 1,800 = $0.700 a bottle today, and $1,260 / 2,100 = $0.600 after.
- Scrap material = 90 x $0.40 / 1,800 = $0.020 a bottle today, and 42 x $0.40 / 2,100 = $0.008 after.
- Total = 0.700 + 0.400 + 0.020 = $1.120 today, against 0.600 + 0.400 + 0.008 = $1.008 after.
- Ten OEE points cut unit cost by $1.120 minus $1.008 = $0.112, or 10.0%.
- Demand stays at 756,000 bottles a month. The line now needs 756,000 / 2,100 = 360 hours instead of 756,000 / 1,800 = 420.
- Scrap saving is cash at once: 756,000 x ($0.020 minus $0.008) = $9,072 a month, or €9,072 in a euro plant.
- The conversion drop is 756,000 x $0.100 = $75,600 a month.
- Of that, 60 x $120 = $7,200 of energy is cash, because the line no longer runs those hours.
- The other $68,400 stays on paper until the freed hours cut a cost.
The decision is about the 60 hours, not the unit cost. They become cash if 126,000 more bottles a month sell, or if they let the plant drop a weekend run or a co-packer. Price extra sales with contribution margin per line-hour.
Until then, only the $9,072 of scrap and the $7,200 of energy are money in the bank.
Mistakes plants make with OEE and unit cost
- Reading a lower unit cost as cash before volume or spending changes.
- Dividing line cost by total units instead of good units.
- Leaving scrap material out, so quality losses look free.
- Setting standard cost on the planned rate, not the measured one.
- Comparing unit cost across plants that define OEE differently.
Where Fabrico fits
Fabrico is a computer vision enabled Manufacturing Performance Platform. OEE and light MES come first, so good units per hour and the cost of each loss come from the line itself.
- Every loss priced in money, so stops, slow running and rejects each show their cost.
- Losses ranked by money, so a reject that wastes material rises above a cheaper stop.
- OEE live by line and shift, with good units per hour measured, not planned.
- The operator confirms the reason in one tap, so each reject and stop has a cause.
You start on one line, with a baseline and a decision date agreed in advance. There is no free plan and there are no tiers: each plant gets a quote. Book a demo to see what drives unit cost on your line.
Frequently asked questions
Why does unit cost rise when volume drops, even at the same OEE?
Because most of the line's cost is fixed for the month. Crew, overhead and depreciation are paid whether the line runs or not. When volume drops, fewer units carry the same monthly cost, so each unit's share rises. OEE shows how well the line ran its hours; volume decides how many hours it ran.
How do you calculate conversion cost per unit?
Add up what it costs to run the line for an hour: labour, energy, overhead and depreciation. Divide by the good units the line made in that hour, from machine counts. Use good units, not total units, or rejects will look like output and the cost will look too low.
Does higher OEE always reduce unit cost?
On the cost sheet, yes: fixed hourly costs spread over more good units. In cash terms, only if the extra output sells or a real cost goes, such as overtime or a shift. If the plant makes the same volume in fewer hours, little changes except scrap and the energy of the hours it no longer runs.
Should scrap be included in cost per unit?
Yes. Rejects use material that the good units must pay for, so spread scrap material over the good units shipped. Count it once, at material cost. The lost line time for those rejects is already inside OEE, so adding their full margin as well would count the same loss twice.
What is the difference between cost per unit and cost per good unit?
Cost per unit divides cost by everything the line made, rejects included. Cost per good unit divides it by saleable units only. The second is the honest number, because customers only pay for good units. On a line with many rejects, the gap between the two can be large.
See what your line's losses do to unit cost
Bring one line's monthly cost and output to a demo. We will show which losses raise its unit cost most, and which of them are cash.
Latest from our blog



Real Fabrico tiles, sample data.